Skip to Main Content

insightsarticles

The basics of business valuation: The valuation rocket ship

08.12.24 /

This article is the first in a four-part series based on the book A Field Guide to Business Valuation, written by BerryDunn’s Seth Webber and Casey Karlsen. 

A banner hanging on the wall of a particular consulting firm states, “In God we trust – everyone else, bring data.” The message of this sign is humorous and clear: if one wants people to agree with one’s position, one must provide supporting data. This is particularly true when making major decisions.

Some of the most important decisions a business owner will make are related to the transition of ownership in their business. Yet when they come to the table for these big decisions, people sometimes neglect to bring the most important thing: data. At a minimum, they need to know the value of their business. It would also be beneficial to understand their business’s value drivers, risk profile, profitability drivers, and performance relative to their peers. A thorough business valuation contains this information and more.

Our favorite illustration of the business valuation process is the “valuation rocket ship.” The economic overview, industry analysis, and company overview provide the base to launch the valuation. The different approaches are then used to create three different perspectives on value. All of this information is then synthesized into the conclusion of value.
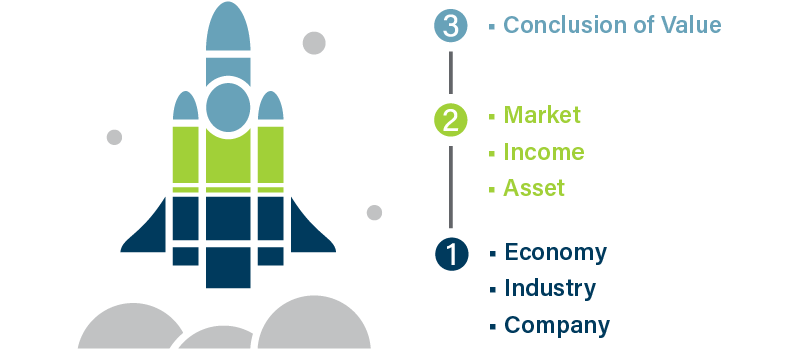
Economy, industry, and subject company analysis

The economic overview sets the groundwork for factors affecting value that are present in the general economy (unemployment rates, inflation, interest rates, etc.). The scope then narrows to the specific industry in which the subject company operates. The industry analysis discusses factors such as historical performance for the industry, supply chain risks, and barriers to entry. Valuation reports then get to the heart of the matter: the subject company. This analysis includes the history, ownership, risks, and other factors that may affect value.

Analysts carefully study the subject company to identify the features that affect value in an actual or hypothetical sale of the business. Acquirers need to know how a company operates and what factors may affect its viability and profitability moving forward. Analysts spend a lot of time looking for items that affect the risk profile of a company. Risk and business value are like children playing on a see-saw: As risk goes up, value goes down.

Once these analyses are complete, the data is considered through different lenses to get a complete picture. Businesses are commonly valued using three common approaches: The market approach, the income approach, and the asset approach, as we’ll discuss below.

Market approach

To understand the market approach, an analogy to the appraisal of real estate may be useful. If one is interested in buying a house, one could look at the price of similar houses to estimate the value of the house in question. Similarly, if one wishes to value a business, one can estimate its worth through a comparison to the sale of similar businesses.

Income approach

If one is trying to estimate the value of an income-producing property such as an industrial warehouse that will be leased out, one could estimate its value based on how much income it will generate over its life. This is called the income approach. Just like with income-producing properties, business value may be estimated based on how much income businesses are expected to generate.

Asset approach

A third way to value a building is by looking at how much it would cost to construct the building rather than buying a completed building. This “make vs. buy” approach is known as the cost approach for real estate appraisals. In the business valuation community, this approach is known as the asset approach. Rather than looking at the value of the company as it exists today, one could estimate value based on how much it would cost to start a similar company.

Conclusion of value

There is a parable about six blindfolded men who encountered an elephant for the first time. They each inspected the elephant by touching it with their hands. The first man felt the elephant’s trunk and concluded that an elephant was a type of large snake. The second man reached the elephant’s ear and stated that an elephant must be a type of fan. The third man felt the elephant’s leg, noting that an elephant is like a tree trunk. The fourth man, feeling the elephant’s side, thought that an elephant was like a wall. The fifth man felt the elephant’s tail and opined that an elephant is a type of rope. The last man felt the elephant’s tusk and decided that an elephant must be like a spear.

As this parable illustrates, when we have a narrow focus and consider only one perspective, we arrive at faulty conclusions. We can make this error in business valuations if we apply only one method to value a company. Each valuation method provides us with a different perspective on value. By considering several different methods, we can get a clear picture of what the subject company is worth.

BerryDunn’s Business Valuation Group partners with clients to bring clarity to the complexities of business valuation while adhering to strict development and reporting standards. We render an independent, objective opinion of your company’s value in a reporting format tailored to meet your needs. We thoroughly analyze the financial and operational performance of your company to understand the story behind the numbers. We assess current and forecasted market conditions as they impact present and future cash flows, which in turn drives value. Learn more about our team and services. 

Related Professionals

Leaders

“BerryDunn’s Valuation Services Team is a professional powerhouse. We were truly impressed with the level of detailed analysis, critical thought and consistent communication that yielded important insights as we navigated our largest private acquisition to date. We were grateful to have an immediately responsive team lead who was able to bring in subject matter experts as needed to uncover and analyze all facets of the business and ultimately synthesize those findings into a clear, digestible, and accurate valuation report. We look forward to working with this all-star team on our next transaction and confidently recommend that others put their trust in their capable hands.”
 
Kir Harris
Acquisitions Lead
Mastway, LLC

Testimonial
A clear, digestible, and accurate valuation report

Executive compensation, bonuses, and other cost structure items, such as rent, are often contentious issues in business valuations, as business valuations are often valued by reference to the income they produce. If the business being valued pays its employees an above-market rate, for example, its income will be depressed. Accordingly, if no adjustments are made, the value of the business will also be diminished.

When valuing controlling ownership interests, valuation analysts often restate above- or below-market items (compensation, bonuses, rent, etc.) to a fair market level to reflect what a hypothetical buyer would pay. In the valuation of companies with ESOPs, the issue gets more complicated. The following hypothetical example illustrates why.

Glamorous Grocery is a company that is 100% owned by an ESOP. A valuation analyst is retained to estimate the fair market value of each ESOP share. Glamorous Grocery generates very little income, in part because several executives are overcompensated. The valuation analyst normalizes executive compensation to a market level. This increases Glamorous Grocery’s income, and by extension the fair market value of Glamorous Grocery, ultimately resulting in a higher ESOP share value.

Glamorous Grocery’s trustee then uses this valuation to establish the market price of ESOP shares for the following year. When employees retire, Glamorous Grocery buys employees out at the established share price. The problem? As mentioned before, Glamorous Grocery generates very little income and as a result has difficulty obtaining the liquidity to buy out employees.

This simple example illustrates the concerns about normalizing executive compensation in ESOP valuations. If you reduce executive compensation for valuation purposes, the share price increases, putting a heavier burden on the company when you redeem shares. The company, which already has reduced income from paying above-market executive compensation, may struggle to redeem shares at the established price.

While control-level adjustments may be common, it is worth considering whether they are appropriate in an ESOP valuation. It is important that the benefit stream reflect the underlying economic reality of the company to ensure longevity of the company and the company’s ESOP.

Questions? Our valuation team will be happy to help. 

BerryDunn’s Business Valuation Group partners with clients to bring clarity to the complexities of business valuation, while adhering to strict development and reporting standards. We render an independent, objective opinion of your company’s value in a reporting format tailored to meet your needs. We thoroughly analyze the financial and operational performance of your company to understand the story behind the numbers. We assess current and forecasted market conditions as they impact present and future cash flows, which in turn drives value.

Article
Compensation, bonuses, and other factors that can make or break an Employee Stock Ownership Plan (ESOP)

While a massive number of people are retiring each year and counting on the value of their business as part of their retirement plan, many are unable to actually generate any liquidity beyond normal compensation. They may even have a very valuable business, but can’t convert any of that value into cash. What a terrible situation! They may feel like a sailor stranded on a desert island—surrounded by water, but dying of thirst.

Attaining liquidity from your business and increasing business value are two topics that go hand in hand. Factors that increase business value often also increase the ease of selling the business. Even if your plan is to never sell, increasing profitability and liquidity will make planning easier. In this blog post, we will identify five ways business owners can improve business value and increase the likelihood of selling the business at a desirable price.

Businesses are often valued by using an income metric (such as earnings before interest, taxes, depreciation, and amortization, or EBITDA) and a valuation pricing multiple.


To increase business value, business owners can increase the valuation pricing multiple, increase income, or both. Focusing on improving the multiple is often a more effective way to increase business value.

Business risk is the key driver of the multiple. Five effective ways to improve the multiple are:

  1. Reduce reliance on the owner of the business
  2. Incentivize key employees to sign long-term employment contracts
  3. Diversify the customer base
  4. Create sustainable recurring revenue 
  5. Maintain immaculate financial statements

By planning ahead and implementing the above steps, business owners may be in a much better position for retirement.

P.S. We host a regular value acceleration presentation series. Please contact me or visit our event calendar to learn more. We would love to have you attend. These presentations focus on the process to increase the value of your business and build liquidity into your life.

Article
Value acceleration—The gas pedal for the value of your business

I leaned out of my expansive corner office (think: cubicle) and asked my coworker Andrew about an interesting topic I had been thinking about. “Hey Andrew, do you know what BATNA stands for?” I asked. Andrew, who knows most things worth knowing, indicated that he didn’t know. This felt good, as there are very few things that I know that Andrew doesn’t. 

BATNA, which stands for “best alternative to no agreement”, is very relevant to business owners who may at some point want to sell their business. It’s a relatively simple concept with significant implications in the context of negotiations, as the strength of your negotiating position depends on what happens if the deal falls through (i.e., if there is no agreement). Put another way, your negotiating position is dependent on your "next best alternative", but I’m pretty sure the acronym NBA is already being used.

If you have 100 potential buyers lined up, you have a strong negotiating position. If the first buyer backs out of the deal, you have 99 alternatives. But if you have only one potential buyer lined up, you have a weak negotiating position. Simple, right?

BATNA is applicable to many areas of our life: buying or selling a car, negotiating the price of a house, or even choosing which Netflix show to watch. Since I specialize in valuations, let’s talk about BATNA and valuations, and more specifically, fair market value versus investment value.

Fair Market Value

The International Glossary of Business Valuation Terms defines fair market value as “the price, expressed in terms of cash equivalents, at which property would change hands between a hypothetical willing and able buyer and a hypothetical willing and able seller, acting at arm’s length in an open and unrestricted market, when neither is under compulsion to buy or sell and when both have reasonable knowledge of the relevant facts.”

Think about fair market value as the price that I would pay for, for example, a Mexican restaurant. I have never owned a Mexican restaurant, but if the restaurant generates favorable returns (and favorable burritos), I may want to buy it. Fair market value is the price that a hypothetical buyer such as myself would pay for the restaurant. 

Investment Value

The International Glossary of Business Valuation Terms defines investment value as “the value to a particular investor based on individual investment requirements and expectations.”

Think about investment value as the price that the owner of a chain of Mexican restaurants would pay for a restaurant to add to their portfolio. This strategic buyer knows that because they already own a chain of restaurants, when they acquire this restaurant, they can reduce overhead, implement several successful marketing strategies, and benefit from other synergies. Because of these cost savings, the restaurant chain owner may be willing to pay more for the restaurant than fair market value (what I would be willing to pay). As this example illustrates, investment value is often higher than fair market value.

As a business owner you may conclude “Well, if investment value is higher than fair market value, I would like to sell my business for investment value.” I agree. I absolutely agree. Unfortunately, obtaining investment value is not a guaranteed thing because of… you guessed it! BATNA. 

Business owners may identify a potential strategic buyer and hope to obtain investment value in the sale. However, in reality, unless the business owner has identified a ready pool of potential strategic buyers (notice the use of the plural here), they may not be in a negotiating position to command investment value. A potential strategic buyer may realize if they are the only potential strategic buyer of a company, they aren’t competing against anybody offering more than fair market value for the business. If there isn’t any agreement, the business owner’s best alternative is to sell at fair market value. Realizing this, a strategic buyer will likely make an offer for less than investment value. 

If you are looking to sell your business, you need to put yourself in a negotiating position to command a premium above fair market value. You need to identify as many potential buyers as possible. With multiple potential strategic buyers identified, your BATNA is investment value. You will have successfully shifted the focus from a competition for your business to a competition among strategic buyers. Now, the strategic buyers will be concerned with their own BATNA, rather than yours. And that’s a good thing.

We frequently encounter clients surprised by the difficulty of commanding investment value for the sale of their business. BATNA helps explain why business owners are unable to attain investment value. 

At BerryDunn, we perform business valuations under both the investment value standard and the fair market value standard.

If you have any questions about the value of your business, please contact a professional on our business valuation team

Article
BATNA: What you need to know

Do you know what would happen to your company if your CEO suddenly had to resign immediately for personal reasons? Or got seriously ill? Or worse, died? These scenarios, while rare, do happen, and many companies are not prepared. In fact, 45% of US companies do not have a contingency plan for CEO succession, according to a 2020 Harvard Business Review study.  

Do you have a plan for CEO succession? As a business owner, you may have an exit strategy in place for your company, but do you have a plan to bridge the leadership gap for you and each member of your leadership team? Does the plan include the kind of crises listed above? What would you do if your next-in-line left suddenly? 

Whether yours is a family-owned business, a company of equity partners, or a private company with a governing body, here are things to consider when you’re faced with a situation where your CEO has abruptly departed or has decided to step down.  

1. Get a plan in place. First, assess the situation and figure out your priorities. If there is already a plan for these types of circumstances, evaluate how much of it is applicable to this particular circumstance. For example, if the plan is for the stepping down or announced retirement of your CEO, but some other catastrophic event occurs, you may need to adjust key components and focus on immediate messaging rather than future positioning. If there is no plan, assign a small team to create one immediately. 

Make sure management, team leaders, and employees are aware and informed of your progress; this will help keep you organized and streamline communications. Management needs to take the lead and select a point person to document the process. Management also needs to take the lead in demeanor. Model your actions so employees can see the situation is being handled with care. Once a strategy is identified based on your priorities, draft a plan that includes what happens now, in the immediate future, and beyond. Include timetables so people know when decisions will be made.  

2. Communicate clearly, and often. In times of uncertainty, your employees will need as much specific information as you can give them. Knowing when they will hear from you, even if it is “we have nothing new to report” builds trust and keeps them vested and involved. By letting them know what your plan is, when they’ll receive another update, what to tell clients, and even what specifics you can give them (e.g., who will take over which CEO responsibility and for how long), you make them feel that they are important stakeholders, and not just bystanders. Stakeholders are more likely to be strong supporters during and after any transition that needs to take place. 

3. Pull in professional help. Depending on your resources, we recommend bringing in a professional to help you handle the situation at hand. At the very least, call in an objective opinion. You’ll need someone who can help you make decisions when emotions are running high. Bringing someone on board that can help you decipher what you have to work with and what your legal and other obligations may be, help rally your team, deal with the media, and manage emotions can be invaluable during a challenging time. Even if it’s temporary. 

4. Develop a timeline. Figure out how much time you have for the transition. For example, if your CEO is ill and will be stepping down in six months, you have time to update any existing exit strategy or succession plan you have in place. Things to include in the timeline: 

  • Who is taking over what responsibilities? 
  • How and what will be communicated to your company and stakeholders? 
  • How and what will be communicated to the market? 
  • How will you bring in the CEO's replacement, while helping the current CEO transition out of the organization? 

If you are in a crisis situation (e.g., your CEO has been suddenly forced out or asked to leave without a public explanation), you won’t have the luxury of time.  

Find out what other arrangements have been made in the past and update them as needed. Work with your PR firm to help with your change management and do the right things for all involved to salvage the company’s reputation. When handled correctly, crises don’t have to have a lasting negative impact on your business.   

5. Manage change effectively. When you’re under the gun to quickly make significant changes at the top, you need to understand how the changes may affect various parts of your company. While instinct may tell you to focus externally, don’t neglect your employees. Be as transparent as you possibly can be, present an action plan, ask for support, and get them involved in keeping the environment positive. Whether you bring in professionals or not, make sure you allow for questions, feedback, and even discord if challenging information is being revealed.  

6. Handle the media. Crisis rule #1 is making it clear who can, and who cannot, speak to the media. Assign a point person for all external inquiries and instruct employees to refer all reporter requests for comment to that point person. You absolutely do not want employees leaking sensitive information to the media. 
 
With your employees on board with the change management action plan, you can now focus on external communications and how you will present what is happening to the media. This is not completely under your control. Technology and social media changed the game in terms of speed and access to information to the public and transparency when it comes to corporate leadership. Present a message to the media quickly that coincides with your values as a company. If you are dealing with a scandal where public trust is involved and your CEO is stepping down, handling this effectively will take tact and most likely a team of professionals to help. 

Exit strategies are planning tools. Uncontrollable events occur and we don’t always get to follow our plan as we would have liked. Your organization can still be prepared and know what to do in an emergency situation or sudden crisis.  Executives move out of their roles every day, but how companies respond to these changes is reflective of the strategy in place to handle unexpected situations. Be as prepared as possible. Own your challenges. Stay accountable. 

BerryDunn can help whether you need extra assistance in your office during peak times or interim leadership support during periods of transition. We offer the expertise of a fully staffed accounting department for short-term assignments or long-term engagements―so you can focus on your business. Meet our interim assistance experts.

Article
Crisis averted: Why you need a CEO succession plan today

Read this if your CFO has recently departed, or if you're looking for a replacement.

With the post-Covid labor shortage, “the Great Resignation,” an aging workforce, and ongoing staffing concerns, almost every industry is facing challenges in hiring talented staff. To address these challenges, many organizations are hiring temporary or interim help—even for C-suite positions such as Chief Financial Officers (CFOs).

You may be thinking, “The CFO is a key business partner in advising and collaborating with the CEO and developing a long-term strategy for the organization; why would I hire a contractor to fill this most-important role?” Hiring an interim CFO may be a good option to consider in certain circumstances. Here are three situations where temporary help might be the best solution for your organization.

Your organization has grown

If your company has grown since you created your finance department, or your controller isn’t ready or suited for a promotion, bringing on an interim CFO can be a natural next step in your company’s evolution, without having to make a long-term commitment. It can allow you to take the time and fully understand what you need from the role — and what kind of person is the best fit for your company’s future.

BerryDunn's Kathy Parker, leader of the Boston-based Outsourced Accounting group, has worked with many companies to help them through periods of transition. "As companies grow, many need team members at various skill levels, which requires more money to pay for multiple full-time roles," she shared. "Obtaining interim CFO services allows a company to access different skill levels while paying a fraction of the cost. As the company grows, they can always scale its resources; the beauty of this model is the flexibility."

If your company is looking for greater financial skill or advice to expand into a new market, or turn around an underperforming division, you may want to bring on an outsourced CFO with a specific set of objectives and timeline in mind. You can bring someone on board to develop growth strategies, make course corrections, bring in new financing, and update operational processes, without necessarily needing to keep those skills in the organization once they finish their assignment. Your company benefits from this very specific skill set without the expense of having a talented but expensive resource on your permanent payroll.

Your CFO has resigned

The best-laid succession plans often go astray. If that’s the case when your CFO departs, your organization may need to outsource the CFO function to fill the gap. When your company loses the leader of company-wide financial functions, you may need to find someone who can come in with those skills and get right to work. While they may need guidance and support on specifics to your company, they should be able to adapt quickly and keep financial operations running smoothly. Articulating short-term goals and setting deadlines for naming a new CFO can help lay the foundation for a successful engagement.

You don’t have the budget for a full-time CFO

If your company is the right size to have a part-time CFO, outsourcing CFO functions can be less expensive than bringing on a full-time in-house CFO. Depending on your operational and financial rhythms, you may need the CFO role full-time in parts of the year, and not in others. Initially, an interim CFO can bring a new perspective from a professional who is coming in with fresh eyes and experience outside of your company.

After the immediate need or initial crisis passes, you can review your options. Once the temporary CFO’s agreement expires, you can bring someone new in depending on your needs, or keep the contract CFO in place by extending their assignment.

Considerations for hiring an interim CFO

Making the decision between hiring someone full-time or bringing in temporary contract help can be difficult. Although it oversimplifies the decision a bit, a good rule of thumb is: the more strategic the role will be, the more important it is that you have a long-term person in the job. CFOs can have a wide range of duties, including, but not limited to:

  • Financial risk management, including planning and record-keeping
  • Management of compliance and regulatory requirements
  • Creating and monitoring reliable control systems
  • Debt and equity financing
  • Financial reporting to the Board of Directors

If the focus is primarily overseeing the financial functions of the organization and/or developing a skilled finance department, you can rely — at least initially — on a CFO for hire.

Regardless of what you choose to do, your decision will have an impact on the financial health of your organization — from avoiding finance department dissatisfaction or turnover to capitalizing on new market opportunities. Getting outside advice or a more objective view may be an important part of making the right choice for your company.

BerryDunn can help whether you need extra assistance in your office during peak times or interim leadership support during periods of transition. We offer the expertise of a fully staffed accounting department for short-term assignments or long-term engagements―so you can focus on your business. Meet our interim assistance experts.

Article
Three reasons to consider hiring an interim CFO

Reading through the 133-page exposure draft for the Proposed Statement on Auditing Standards (SAS) Forming an Opinion and Reporting on Financial Statements of Employee Benefit Plans Subject to ERISA, issued back in April 2017, and then comparing it to the final 100+ page standard approved in September 2018, may not sound like a fun way to spend a Sunday morning sipping a coffee (or three), but I disagree.

Lucky for you, I have captured the highlights here. And it really is exciting. Our feedback was incorporated into the final standard both through written comments on the exposure draft and a voice via our firm’s Director of Quality Assurance, who holds a seat on the Auditing Standards Board.

"Limited scope" audits will no longer exist

The debate over the “limited scope” audit has been going on for years. The new standard is designed to help auditors clearly understand their responsibilities in performing an audit, and provide plan sponsors, plan participants, the Department of Labor (DOL), and other interested parties with more information about what auditors do in situations when audits are limited in scope by the plan’s management, which is permitted by DOL reporting and disclosure rules.

Once effective, Audit Committee and Board of Director meetings in which plan financial statements are presented will include more clarity into what an employee benefit plan audit entails, based on revisions to the auditor’s report. I know I would frequently kick off meetings covering the auditor’s report opinion by explaining what a “limited scope” audit was. As a “limited scope” audit will no longer exist, the revised auditor’s report language clearly articulates what the auditor is, and is not, opining on.

When is the new standard effective?

The effective date is “to be determined” as it will be aligned with the new overall auditor’s reporting standard once that is finalized, and the standard does not permit early adoption. So there is still time to educate and prepare all parties involved.

Probably the biggest conversation piece around the water cooler for the new standard is the lingo. The “limited scope” audit language will be going away and now the auditor’s report and all related language will refer to an “ERISA section 103(a)(3)(C)” audit. I know, it’s a mouthful?try and say that one three times fast!

The auditor's report will look much different

The auditor’s report under an ERISA section 103(a)(3)(C) audit will look significantly different from the old “limited scope” auditor’s report, once the standard is effective. There are several illustrative examples of reports included in the standard to refer to. One thing you will immediately notice?the auditor’s report is getting longer and not shorter. Some highlights:

The Opinion section will include two bullets that explicitly state, in basic summarized terms: (1) the certified information agrees to the financial statements, and (2)  the auditor’s opinion on everything else, which the auditor has audited.

Other Matter—Supplemental Schedules Required by ERISA section will include two bullets that explicitly state, in basic summarized terms, (1) the certified information agrees to the financial statements and (2) the auditor’s opinion on everything else, which the auditor has audited in relation to the financial statements. Sound similar to the Opinion section? Well, that’s because it is!).

Other key takeaways

  • Auditors will be required to make inquiries of management to gain assurance they performed procedures to determine the certifying institution is qualified for the ERISA section 103(a)(3)(C) audit, as it is management’s responsibility to make that determination.
  • Fair value disclosures included within the plan’s financial statements are also included under the certification umbrella and subject to the same audit procedures. As an auditor, if anything comes to our attention that does not meet expectations, we would further assess as necessary.
  • The auditor is required to obtain and read a draft Form 5500 prior to issuance of the auditor’s report.

The final standard also removed some highly debated provisions included in the draft proposal as follows:

  • There is no report on findings required, but the auditor is required to follow AU-C 250, AU-C 260 and AU-C 265. Should anything arise that warrants communication to those charged with governance, those findings must be communicated in writing. Be sure to grab another coffee and refresh yourself on AU-C 250, AU-C 260 and AU-C 265!
  • The new required procedures section for an audit was scrapped and replaced with an Appendix A for recommended audit procedures based on risk assessments. There are some great tools there to look at.
  • The required emphasis-of-matter section paragraph section of the auditor’s report was also scrapped.

Questions about the new employee benefit audit standard or employee benefit plan audits

At BerryDunn, we perform over 200 employee benefit plan audits each year. If you have any questions, we would love to help. And we’ll keep the acronyms to a minimum. Please reach out with any questions.

Article
Auditing standards board approves new employee benefit plan auditing standard: What you need to know

When last we blogged about the Financial Accounting Standards Board’s (FASB) new “current expected credit losses” (CECL) model for estimating an allowance for loan and lease losses (ALLL), we reviewed the process for developing reasonable and supportable forecasts for use in establishing the ALLL. Once you develop those forecasts, how does that information translate into amounts to set aside for loan losses?

A portion of the ALLL will continue to be based on specifically identified loans you’re concerned about. For those loans, you will continue to establish a specific component of the ALLL based on your estimate of the loss ultimately expected on the loans.

The tricky part, of course, is estimating an ALLL for the other 99% of the loan portfolio. This is where the forecasts come in. The new rules do not prescribe a particular methodology, and banking regulators have indicated community banks will likely be able to continue with their current approach, adjusted to use appropriate inputs in a manner that complies with the CECL model. One of the biggest challenges is the expectation in CECL that the ALLL will be estimated using the institution’s historical information, to the extent available and relevant.

Following is just one of many ways  you can approach it. I’ve also included a link at the end of this article to an example illustrating this approach.

Step One: Historical Loss Factors

  1. First, for a given subset of the loan portfolio (e.g., the residential loan pool), you might first break down the portfolio by the number of years remaining until expected payoff (via maturity or refinancing). This is important because, on average, a loan with seven years remaining until expected payoff will have a higher level of remaining lifetime losses than a loan with one year remaining. It therefore generally wouldn’t be appropriate to use the same loss factor for both loans.
     
  2. Next, decide on a set of drivers that tend to correlate with loan losses over time. FASB has indicated it doesn’t expect highly mathematical correlation models will be necessary, especially for community banks. Instead, select factors in your bank’s experience indicative of future losses. These may include:
    • External factors, such as GDP growth, unemployment rates, and housing prices
    • Internal factors such as delinquency rates, classified asset ratios, and the percentage of loans in the portfolio for which certain policy exceptions (e.g., loan-to-value ratio or minimum credit score) were granted
       
  3. Once you select this set of drivers, find an historical loss period — a period of years corresponding to the estimated remaining life of the portfolio in question — where the historical drivers best approximate those you’re expecting in the future, based on your forecasts. For that historical loss period, determine the lifetime remaining loss rates of the loans outstanding at the beginning of that period, broken down by the number of years remaining until payoff. (This may require significant data mining, especially if that historical loss period was quite a few years ago.
     
  4. Apply those loss rates to the breakdown derived in (a) above, by years remaining until maturity.

    Step Two: Adjustments to Historical Loss Rates

    The CECL model requires we adjust historical loss factors for conditions that may not be adequately captured by the historical loss period analysis we’ve just described. Let’s say a particular geographical subset of your market area is significantly affected by the economic fortunes of a large employer in that area.  Based on economic trends or recent developments, you might expect that employer to have a particularly bright – or dim – future over the forecast period; accordingly, you forecast loans to borrowers in that area will have losses that differ significantly from the rest of the portfolio.

    The approach for these loans is the same as in the previous step. However:

    These loans would be segregated from the remainder of the portfolio, which would be subject to the general approach in step one. As you think through this approach, there are myriad variations and many decisions to make, such as:

    Our intent in describing this methodology is to help your CECL implementation team start the dialogue in terms of converting theoretical concepts in the CECL model to actual loans and historical experience.

    To facilitate that discussion, we’ve included a very simple example here that illustrates the steps described above. Analyzing an entire loan portfolio under the CECL model is an exponentially more complex process, but the concepts are the same — forecasting future conditions, and establishing an ALLL based on the bank’s (or, when necessary, peers’) lifetime loan loss experience under similar historical conditions.

    Given the amount of number crunching and analysis necessary, and the potentially significant increase in the ALLL that may result from a lifetime-of-loan loss model, it’s safe to say the time to start is now! If you have any questions about CECL implementation, please contact Tracy Harding or Rob Smalley.

    Other resources
    For more information on CECL, check out our other blogs:

    CECL: Where to Start
    CECL: Bank and Branch Acquisitions
    CECL: Reasonable and Supportable

    To sign up to receive notification of our next CECL update, click here.

    • In substep (c), you would focus on forecasted conditions (such as unemployment rate and changes in real estate values) in the geographical area in which the significant employer is located.
    • You would then select an historical loss period that had actual conditions for that area that best correspond to those you’ve just forecasted.
    • In substep (d), you would determine the lifetime remaining loss rates of loans outstanding at the beginning of that period.
    • In substep (e), you would apply those rates to loans in that geographic area.
    • How to break down the portfolio
    • Which conditions to analyze
    • How to analyze the conditions for correlation with historical loss periods
    • Which resulting loss factors to apply to which loans
Article
CECL implementation: So, you've developed reasonable and supportable forecasts — now what?